
Trade Fragmentation Moves From Policy Debate to Corporate Cost Structure
The most consequential business development is the widening U.S.–China trade confrontation, reinforced by a failed G20 effort to establish common rules on industrial overcapacity and forced labor. Washington has slowed licenses for aircraft parts shipped to China and is preparing additional measures aimed at excess production, while trade ministers in Milwaukee failed to reach consensus on a broader framework.
The immediate market effect is concentrated in aerospace, advanced manufacturing, steel, machinery, logistics and technology. The larger consequence is structural: companies are being pushed to treat export controls, tariffs and supply-chain duplication as permanent operating costs rather than temporary political friction.
Aerospace Becomes a New Pressure Point
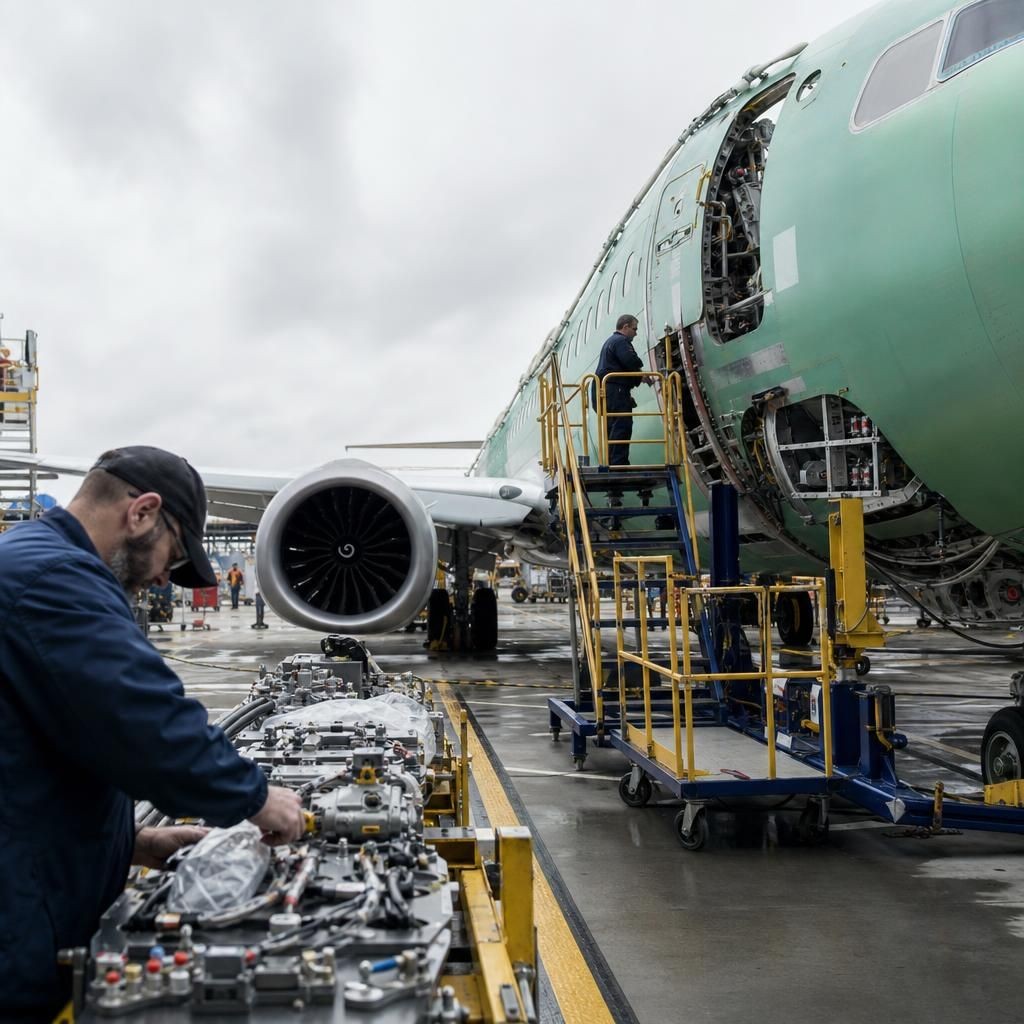
U.S. authorities have recently slowed export licensing for airplane parts bound for China, with approvals reportedly limited to state-owned Commercial Aircraft Corporation of China, or COMAC. Washington is also drafting restrictions on aviation hydraulic-fluid shipments, according to reporting published October 5.
For U.S. aerospace suppliers, the policy creates a mixed earnings picture. Restrictions can reduce near-term sales volumes to Chinese customers, delay shipments and increase compliance expenses. However, they may also strengthen the negotiating position of U.S. manufacturers and support domestic or allied-country sourcing if Chinese aircraft production remains dependent on American components.
The commercial risk is that licensing uncertainty disrupts planning even where individual products are not ultimately prohibited. Aerospace programs operate on long production cycles, and a delayed component can affect assembly schedules, working capital and contractual delivery commitments. Suppliers may respond by holding larger inventories, qualifying alternative customers and separating China-related production from other global operations.
Overcapacity Dispute Raises Tariff Risk
G20 trade ministers failed to agree on measures addressing excess industrial capacity and forced labor in supply chains. U.S. Trade Representative Jamieson Greer said the United States would continue working with like-minded countries to respond to production surpluses, particularly in sectors associated with China.
A proposed Milwaukee Framework called for stronger trade barriers against steel imports from countries with substantial excess capacity. Earlier discussions among 28 mostly Western countries also focused on additional steel tariffs and a possible reconsideration of the World Trade Organization’s most-favored-nation system.
For U.S. businesses, the significance extends beyond steel. A coordinated tariff response could affect aluminum, machinery, electric vehicles, batteries, chemicals and other manufactured goods. Import-competing producers may gain pricing power and market share, while downstream companies could face higher input costs. Construction, transportation equipment and industrial manufacturers would be especially exposed if tariffs raise the cost of basic materials without a corresponding increase in end-market demand.
The absence of a G20 agreement increases the likelihood of a patchwork system. Instead of one predictable multilateral rulebook, companies may face different tariffs, local-content standards and labor-screening requirements across trading blocs. That fragmentation makes procurement less efficient and complicates long-term capital allocation.
Corporate Earnings Effects
The earnings impact will vary by sector, but three channels are most important: revenue exposure, input costs and capital intensity.
Revenue exposure: Companies selling aircraft components, industrial equipment, semiconductors or other controlled products to China may experience delayed orders or reduced addressable markets.
Input costs: Tariffs on metals and manufactured components can compress gross margins when businesses cannot immediately pass higher costs to customers.
Capital intensity: Supply-chain duplication requires new warehouses, qualification programs, regional factories and working capital, lowering near-term returns on invested capital.
Large companies with diversified supplier networks and stronger balance sheets are better positioned to absorb these pressures. Smaller manufacturers may lack the cash to maintain parallel production lines or carry additional inventory. The result could be further industry consolidation, with scale becoming more valuable in procurement, regulatory compliance and geopolitical risk management.
Investors will likely focus on management commentary regarding tariff pass-through, inventory levels, China exposure and capital expenditure. A company that reports stable revenue but rising inventory and logistics expense may be experiencing an early margin problem. Conversely, suppliers with qualified production in North America or allied economies may capture share as customers prioritize resilience over the lowest nominal cost.
Supply Chains Are Being Reconfigured, Not Simply Relocated
The current policy direction does not imply an immediate end to China-linked manufacturing. China remains deeply integrated into global production, and replacing established supplier ecosystems can require years. Instead, companies are adopting layered strategies: retaining Chinese capacity for local demand, adding production in Southeast Asia or Mexico, and increasing final assembly or critical-component manufacturing in the United States and other allied markets.
This model provides flexibility but adds complexity. Businesses must maintain multiple supplier qualification systems, track the origin of components and demonstrate compliance with evolving export-control and forced-labor requirements. Transportation routes may also become less efficient when goods are routed through additional countries or when companies hold safety stock closer to end markets.
The resulting cost inflation is not necessarily visible in headline freight rates. It may appear through duplicated engineering teams, higher insurance premiums, legal fees, customs delays, cybersecurity controls and idle capacity. These expenses can weigh on operating margins even when tariffs themselves are modest.
Broader Economic Implications
Trade fragmentation is likely to produce both protective and contractionary effects. Tariffs and industrial policy can support domestic investment in selected sectors by improving the competitive position of U.S. producers. New factories, equipment purchases and infrastructure spending can contribute to employment and regional economic activity.
At the same time, higher import costs function like a tax on downstream businesses and consumers. If manufacturers pass those costs through, inflation may remain higher for industrial goods. If they absorb them, profit margins weaken. If they redesign products around more expensive inputs, productivity can suffer during the transition.
The lack of international agreement also raises uncertainty for monetary and fiscal policymakers. Companies may delay investment until they understand the durability of tariff schedules and export restrictions. That hesitation can reduce the efficiency of capital formation, particularly in industries requiring large multiyear commitments.
For the United States, the strongest economic outcome would depend on targeted measures coordinated with major trading partners. A broad and inconsistent tariff regime would provide less certainty than narrowly defined remedies paired with transparent exemptions, predictable licensing procedures and allied supply-chain agreements.
What Investors Should Monitor
Near-term market attention should center on whether Washington converts the current policy signals into formal restrictions, how China responds, and whether additional countries join a coordinated approach to steel and other overcapacity-sensitive sectors.
Investors should also monitor company disclosures for changes in China revenue, backlog timing, inventory days, supplier concentration and capital expenditure. Aerospace and industrial companies may show the earliest operational effects because their products are highly regulated and embedded in long production cycles. Steel-consuming manufacturers may face the clearest margin pressure if new tariffs are imposed without immediate pricing power.
The central investment distinction is between companies that treat geopolitical risk as a compliance burden and those that use it to strengthen customer relationships, regionalize production and secure scarce capacity. Trade policy is increasingly influencing competitive advantage directly, making supply-chain design a material determinant of earnings quality.
As the G20 deadlock demonstrates, businesses cannot rely on a rapid return to uniform global trade rules. The more likely environment is one of managed fragmentation, in which resilient networks command a premium but require higher upfront spending. That transition may weigh on margins in the short run while rewarding companies that can finance and execute diversification more effectively than their competitors.


