
Hot Inflation, Elevated Yields Keep Fed Path and Equity Valuations in Tension
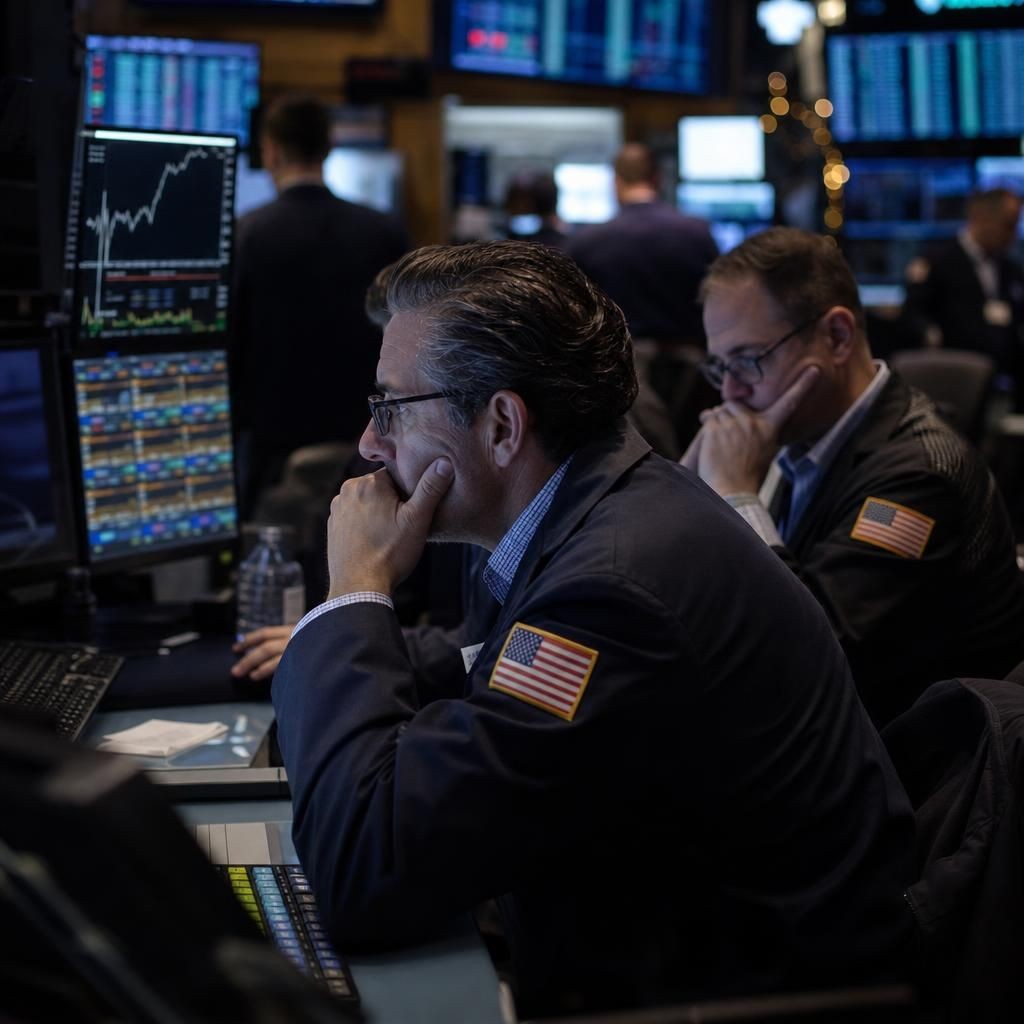
Financial markets entered October 16, 2026, balancing a modest equity rebound against renewed concern that persistent inflation and elevated Treasury yields could constrain the Federal Reserve’s policy options. The S&P 500 was reported at 7,744.06, up 25.12 points, or 0.33%, while futures indicated a mixed session as investors weighed bank earnings, artificial-intelligence exposure, and the cost of capital.
The dominant market issue remains the interaction between inflation and interest rates. Recent hotter-than-expected inflation data have pushed investors to reassess the probability and timing of additional Federal Reserve action, even as market pricing continues to point toward no change at the October 27–28 meeting. That combination—near-term policy stability but a less certain longer-term rate path—has kept bond yields high and equity leadership narrow.
Inflation Keeps the Rate Path Unsettled
Higher inflation readings have raised the hurdle for any rapid easing in financial conditions. A market report indicated that the probability of a rate increase at the late-October meeting rose from the low twenties to approximately 40% or higher after the inflation release, while the 10-year Treasury yield reached 5.3% in the immediate repricing. Subsequent trading showed the yield easing toward 5.085%, illustrating how quickly positioning has shifted between inflation protection and expectations of eventual economic slowing.
Other market commentary described the Federal Reserve as still likely to leave rates unchanged later this month, despite the hotter inflation data. This divergence between policy expectations and bond-market yields is significant. Investors may accept a near-term pause while demanding greater compensation to hold longer-dated government debt, particularly if inflation remains sticky, fiscal supply stays heavy, or the economy proves more resilient than expected.
Money markets were also reported to be pricing three Federal Reserve rate hikes over the following 12 months. Whether that pricing reflects actual expectations or hedging demand, it signals that the market is no longer treating the policy outlook as a straightforward easing cycle. The result is a higher sensitivity across asset classes to every inflation, labor-market, and activity release.
Equities: Relief Rally, Not Yet a Broad Risk Reset
The S&P 500’s 0.33% gain provided evidence of resilience, but the composition of the session matters more than the headline index move. Bank earnings have started the third-quarter reporting season on a mixed footing, and U.S. banks were described as entering correction territory. Financial shares are particularly sensitive to the yield curve, credit conditions, loan demand, and the valuation of securities portfolios, making bank results an important test of whether high rates are supporting net interest income or increasingly damaging balance-sheet flexibility.
Artificial-intelligence stocks have faced separate pressure. A market preview attributed weakness in AI-related equities to concerns about higher borrowing costs amid surging Treasury yields. The sensitivity is understandable: companies priced on long-duration growth assumptions are more exposed to a rise in the discount rate because a larger share of their valuation depends on cash flows expected further in the future.
Barclays commentary that the strongest phase of the AI trade may have passed added to the debate over market concentration and earnings expectations. That does not by itself invalidate the structural investment case for AI, but it raises the standard for subsequent results. Revenue growth, capital expenditure discipline, margins, and evidence of monetization are likely to matter more as investors become less willing to pay expanding multiples for thematic exposure alone.
The immediate equity implication is a market caught between earnings support and valuation pressure. Strong bank results or credible corporate guidance can stabilize risk appetite, but a sustained rise in real yields would continue to challenge richly valued growth stocks. Conversely, a decline in yields could provide relief to technology and other long-duration segments, provided the decline reflects improving inflation expectations rather than a sharp deterioration in growth.
Bonds: The 5% Threshold Is Becoming a Market Variable
The 10-year Treasury yield’s move toward and above 5% has transformed the bond market into a direct competitor for equity capital. At sufficiently attractive yields, investors can earn more income from government securities while taking less credit risk than in corporate or equity markets. That dynamic can compress equity multiples even when earnings estimates remain stable.
Market commentary identified 5.2% as a level that could renew pressure on the dollar and emerging-market currencies if the 10-year yield moves back above it. The threshold is not a formal policy boundary, but it functions as a practical reference point for positioning. A break higher could tighten global financial conditions, increase funding costs, and amplify volatility in interest-rate-sensitive sectors such as housing, utilities, real estate, and highly leveraged companies.
At the same time, the reported easing in yields demonstrates that demand for duration has not disappeared. Investors may still buy Treasuries when equity volatility rises or when they believe restrictive policy will eventually weaken economic activity. This creates a two-way market: inflation surprises push yields higher, while risk aversion and expectations of future slowing can generate sharp bond rallies.
Currency Markets: Dollar Support Versus Policy Uncertainty
Elevated U.S. yields remain a source of support for the dollar because they improve the relative return available on dollar-denominated assets. The relationship is especially important for emerging markets, where a stronger dollar can increase the local-currency burden of external debt and encourage capital outflows. The reported connection between a 10-year yield above 5.2% and renewed pressure on currencies such as the Brazilian real highlights this transmission channel.
Currency moves are nevertheless being moderated by changing expectations for the Federal Reserve. If markets believe higher yields reflect eventual economic weakness rather than a prolonged period of restrictive policy, the dollar’s support can weaken. The reported decline in dollar-yen alongside lower Treasury yields illustrates that interest-rate differentials remain central to foreign-exchange positioning.
For multinational U.S. companies, a stronger dollar can create a headwind when foreign revenue is translated back into dollars. The effect is not uniform: exporters and companies with substantial overseas operations may face earnings pressure, while domestic companies can benefit from cheaper imported goods and lower translated costs. Currency volatility therefore adds another variable to third-quarter guidance.
Investor Sentiment and the Near-Term Outlook
Investor sentiment is being shaped less by a single market direction than by uncertainty around the distribution of outcomes. The possibility of unchanged policy at the October meeting offers some near-term stability, but the inflation data and elevated yields have reduced confidence that monetary easing will proceed smoothly. That tension encourages shorter holding periods, greater factor rotation, and a preference for companies with visible cash flow and stronger balance sheets.
Bank earnings will remain a practical test of economic resilience. Results that show healthy credit quality, stable funding, and durable fee income could support the view that the economy can absorb restrictive policy. Conversely, signs of weakening loan demand, rising provisions, or pressure on securities portfolios would reinforce concerns that high yields are beginning to transmit more forcefully into corporate and household finances.
For equity investors, the key signal is whether earnings growth can outrun the valuation effect of higher discount rates. For bond investors, the focus is whether inflation keeps yields elevated or whether slowing activity eventually creates a sustained rally. Currency investors will continue monitoring the interaction between Treasury yields, Fed expectations, and global risk appetite.
Conclusion
The October 16 market backdrop is best characterized as cautiously resilient rather than decisively bullish. Equities have rebounded, but high Treasury yields and mixed bank earnings limit the durability of a broad risk rally, while AI-related volatility shows that investors are demanding stronger fundamental evidence for premium valuations. Until inflation moderates convincingly or yields retreat for reasons that do not signal a severe growth shock, markets are likely to remain highly responsive to each economic release and earnings update.