
Higher Yields and AI Risk Reprice U.S. Markets
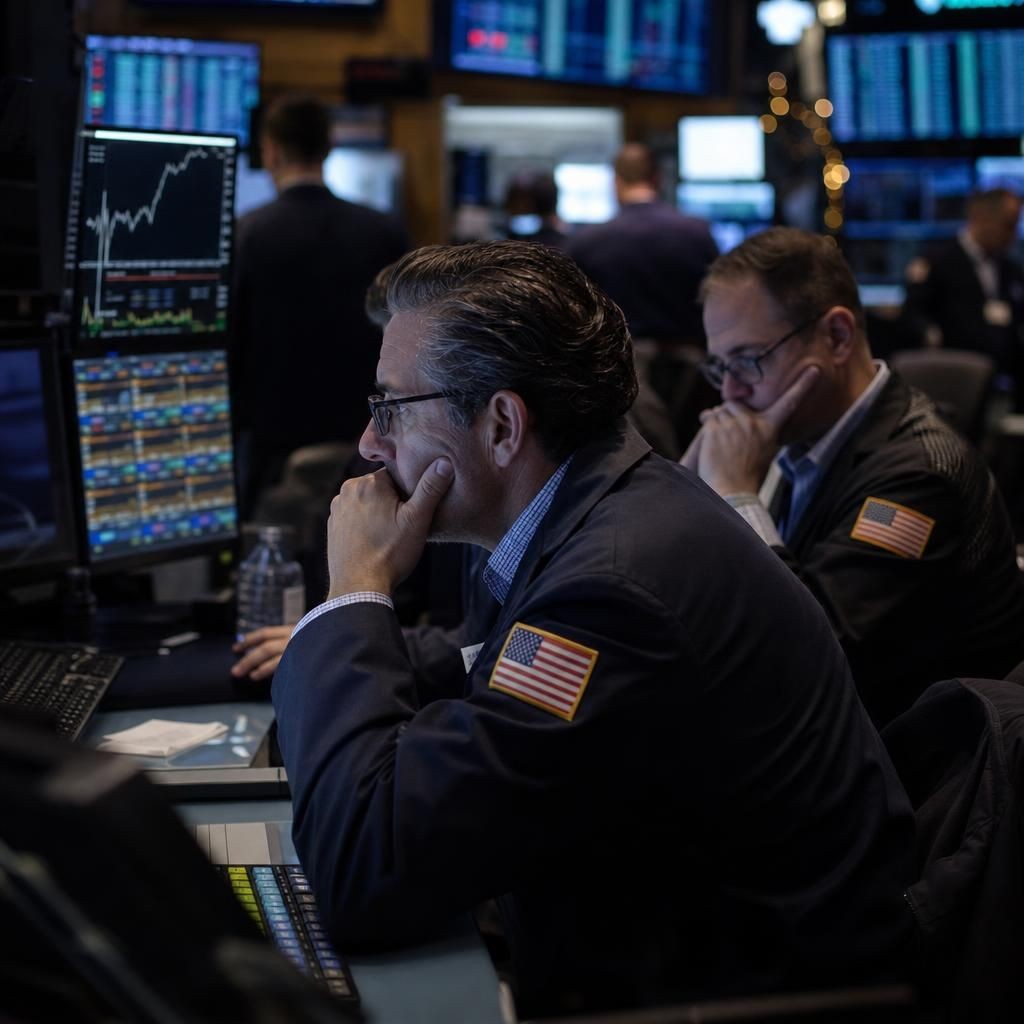
U.S. financial markets entered the October 17 session under pressure as rising Treasury yields, a firmer dollar, higher oil prices and renewed concerns about the financing needs of artificial-intelligence infrastructure companies combined to weaken risk appetite. The latest move represents a broad repricing of duration and growth exposure rather than an isolated equity-sector rotation.
Equities Face a Two-Sided Challenge
The S&P 500 and Nasdaq Composite both ended lower on October 16 and recorded weekly declines, while the Dow Jones Industrial Average posted a weekly gain. Semiconductor stocks were among the weakest performers as investors reassessed the durability of the AI investment cycle and the ability of debt-heavy infrastructure businesses to generate sufficient returns to service their obligations.
The market reaction reflects the sensitivity of high-growth equities to both earnings expectations and discount rates. Companies whose valuations depend on profits far in the future are particularly exposed when long-term government yields rise. Higher financing costs also affect data-center developers, cloud providers and chip buyers, potentially increasing the capital required to expand computing capacity while reducing the present value assigned to projected cash flows.
Oil has added a second source of pressure. Higher energy prices can lift headline inflation, reduce household purchasing power and raise operating costs for transportation, manufacturing and other energy-intensive industries. That combination complicates the equity outlook: nominal revenues may benefit in selected energy companies, but broader corporate margins and consumer demand can weaken if the increase persists.
Treasury Yields Narrow the Federal Reserve’s Options
The benchmark 10-year Treasury yield traded above 5.09% late on October 16, approximately two basis points higher than the prior close. The 2-year yield, which is more directly linked to expectations for monetary policy and inflation, rose 7.2 basis points to 4.87%. The divergence between elevated short- and long-term yields indicates that investors are demanding greater compensation for inflation, policy uncertainty and the fiscal supply of government debt.
Higher yields do not necessarily imply an immediate policy move, but they tighten financial conditions independently of the Federal Reserve. Mortgage rates, corporate borrowing costs and equity discount rates generally respond to Treasury benchmarks. As a result, the bond market can deliver a de facto tightening impulse even while policymakers hold the federal-funds target unchanged.
Market commentary has also pointed to the possibility that persistent inflation pressure could keep the Fed’s future path restrictive. Standard Chartered’s weekly outlook placed the 10-year yield in a 5.00% to 5.25% range and said the dollar should remain supported as markets reassess the prospect of additional Fed hikes. That range would leave duration-sensitive assets vulnerable to further volatility, particularly if incoming inflation or labor-market data remain firm.
The Dollar Gains on Relative Policy Expectations
The U.S. dollar rose 0.68% against a basket of currencies on October 17, reaching its highest level since April 2025. Currency strength is consistent with a market that is assigning relatively higher policy and yield support to U.S. assets. It can also reinforce the pressure on multinational U.S. companies by reducing the dollar value of overseas revenue when earnings are translated back into the reporting currency.
A stronger dollar has mixed macroeconomic consequences. It can reduce the domestic cost of imported goods and provide some relief against imported inflation, but it can also tighten global financial conditions for borrowers with dollar-denominated liabilities. Emerging-market assets may face additional pressure if capital moves toward higher-yielding U.S. instruments, particularly where local currencies are already vulnerable to elevated energy costs.
For U.S. investors, the dollar’s advance offers a partial defensive offset to equity weakness, especially for unhedged international holdings. For corporate America, however, prolonged appreciation could become a headwind to overseas competitiveness and reported earnings growth.
Investor Sentiment Shifts From Expansion to Resilience
The market’s response to AI concerns and oil prices suggests that investors are becoming less willing to pay premium valuations for growth without visible cash-flow support. The concern is not that AI demand has disappeared; rather, the immediate question is whether the scale and timing of capital spending can produce returns before financing costs and competitive pressures erode profitability.
This distinction matters for portfolio construction. Profitable companies with strong balance sheets, pricing power and manageable refinancing needs may be better positioned than businesses dependent on continuous access to inexpensive credit. Energy producers can benefit from higher crude prices, while banks may gain from wider lending spreads, although both sectors remain exposed to economic deterioration and credit losses.
Defensive industries may also attract interest if investors continue to reduce exposure to long-duration technology shares. Yet defensiveness is not synonymous with immunity. Utilities, real estate and other yield-sensitive sectors can suffer when Treasury yields rise, while consumer companies may face pressure if energy costs reduce disposable income.
Cross-Asset Implications
Equities: High-multiple technology and semiconductor stocks remain most exposed to rising discount rates, leveraged AI investment and weaker risk appetite. Energy and value-oriented sectors may provide relative support, but market breadth could remain fragile.
Bonds: Treasury prices remain vulnerable if inflation expectations rise or investors demand greater compensation for fiscal and term risk. The 5.00% to 5.25% range identified for the 10-year yield would preserve pressure on duration-heavy portfolios.
Currencies: The dollar’s strongest level since April 2025 reflects its yield advantage and defensive appeal. Continued appreciation would tighten conditions for overseas borrowers and pressure U.S. multinational earnings.
Investor sentiment: Positioning is shifting toward balance-sheet quality, near-term cash generation and sectors with direct exposure to stronger commodity prices. Volatility is likely to remain elevated while investors distinguish temporary risk aversion from a durable change in the earnings outlook.
What Markets Will Watch Next
The immediate focus will be on evidence that can clarify whether the current repricing is principally inflation-driven or growth-driven. Further increases in short-term yields would signal rising expectations for a more restrictive Fed, while a sharp rise in long-term yields without a comparable move in the front end could point more strongly to term-premium and fiscal concerns.
Investors will also monitor crude-oil developments, inflation expectations, corporate guidance and funding conditions for AI infrastructure. A stabilization in yields and energy prices could allow technology shares to recover, but a continuation of both trends would increase the probability of broader earnings downgrades and further valuation compression.
Conclusion
The latest sell-off links three market forces that had previously been treated as separate: restrictive monetary expectations, elevated energy costs and questions about the economics of AI investment. With the 10-year yield above 5.09%, the 2-year yield near 4.87% and the dollar at its highest level since April 2025, financial conditions are clearly less forgiving.
For equities, the environment favors earnings quality over distant growth promises. For bonds, the central risk remains that inflation and fiscal uncertainty keep yields elevated. For currencies, the dollar’s strength reflects defensive demand and relative U.S. yield support. Until those pressures ease, investors are likely to reward resilient cash flows and disciplined balance sheets while treating highly valued, debt-dependent growth exposure with greater caution.