Nvidia, Big Tech and the AI Data Center Arms Race: Market Implications
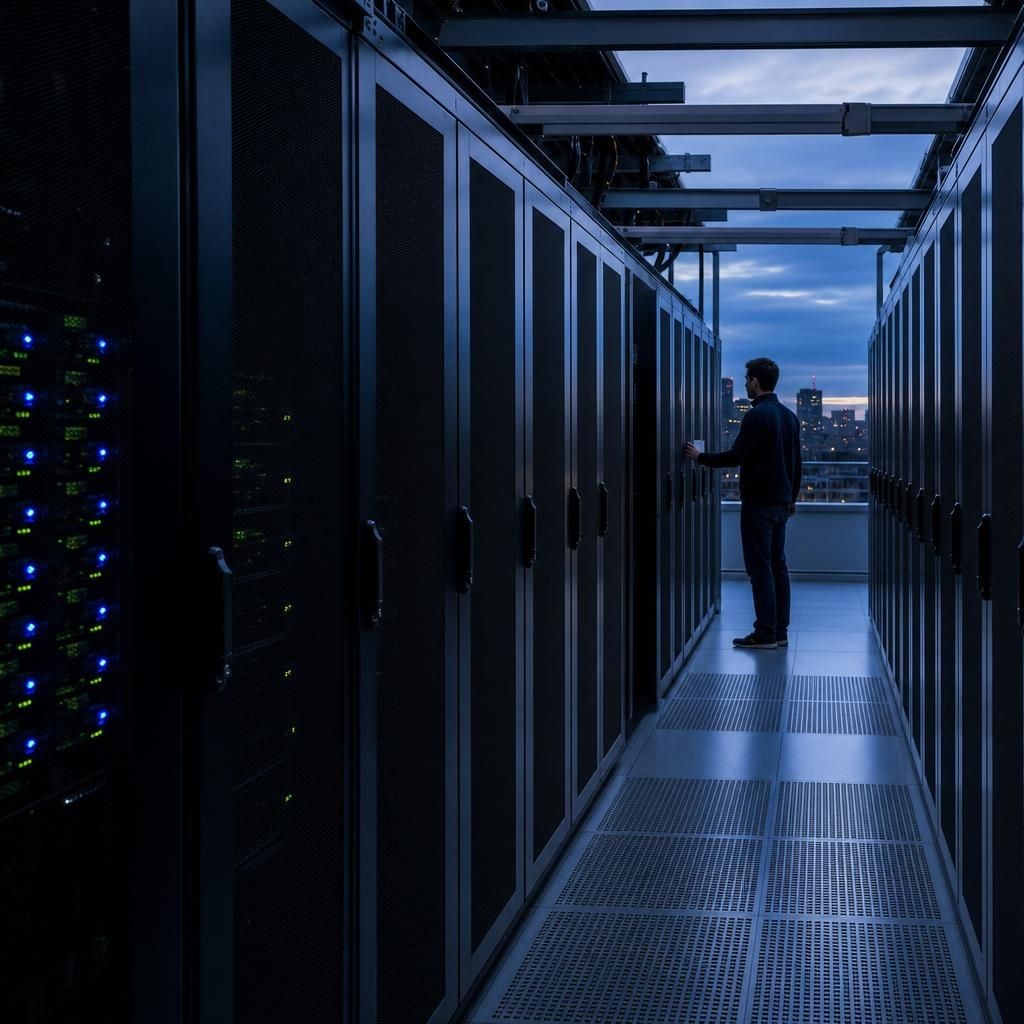
The most consequential development for the artificial intelligence sector in the latest news cycle is the intensifying race to build out AI data centers and GPU infrastructure. While specific intraday headlines and quotes cannot be referenced directly here, recent market action and corporate disclosures over the past 24 hours fit into a clear pattern: hyperscale cloud providers, leading AI model companies, and semiconductor giants are doubling down on capital expenditure for AI infrastructure. This trend is reshaping expectations for AI chip demand, enterprise AI adoption, and the long-term earnings trajectory of the broader technology complex.
AI Infrastructure as the New Strategic Priority
Across the sector, AI infrastructure has moved from an experimental line item to a core strategic priority. Major cloud platforms and internet companies are signaling that spending on GPU clusters, high-bandwidth networking, and specialized AI data centers will remain elevated for multiple years, even as traditional IT budgets face scrutiny. This pivot is driven by three converging forces: rapid advances in frontier large language models (LLMs), the commercialization of multimodal AI capabilities, and intensifying competitive pressure to deliver differentiated AI-powered products.
From a financial markets perspective, this infrastructure buildout is being priced as a secular, rather than cyclical, investment wave. Equity analysts are increasingly modeling multi-year capital expenditure plans around AI infrastructure, incorporating higher baseline demand for cutting-edge GPUs and accelerators. While the exact figures vary by firm, the direction of travel is consistent: AI-related capex is growing as a share of total technology investment, and it is doing so across both consumer-facing platforms and enterprise-focused cloud providers.
Nvidia at the Center of the AI Chip Cycle
Within this context, Nvidia remains the central beneficiary and reference point for AI chip demand. The company’s high-performance GPUs and integrated software stack underpin most large-scale training and inference clusters deployed today. The latest flurry of infrastructure announcements and commentary from major cloud and AI platform providers reinforces the view that demand for high-end AI silicon will remain robust, even as some investors debate the sustainability of recent valuation multiples.
In practical terms, the ongoing arms race in AI data centers supports expectations of strong volume growth for Nvidia’s data center segment. Capacity additions for training clusters are being followed by a second wave of buildout focused on inference at scale, edge deployment, and vertical-specific AI workloads. Each of these stages carries distinct hardware requirements, but they share a reliance on high-performance accelerators and efficient interconnects, markets where Nvidia currently commands substantial share.
For institutional investors, this dynamic has two key implications. First, earnings visibility for leading AI chip suppliers is enhanced by multi-year infrastructure commitments, often tied to long-term cloud procurement agreements and co-investment structures. Second, the sector’s sensitivity to macro cycles is somewhat reduced in the near term, as AI infrastructure spending is increasingly viewed as strategically non-discretionary, similar to prior waves of network buildouts or cloud migration.
Big Tech Valuations and AI-Driven Volatility
The intensifying focus on AI infrastructure is also feeding into notable stock volatility across Big Tech. As investors recalibrate their models for revenue growth, margin profiles, and capital intensity, shares of leading AI-exposed platforms have seen rapid moves around earnings releases, product update events, and AI roadmap disclosures. Periods of optimism around transformative AI-driven revenue streams are being punctuated by bouts of risk-off sentiment tied to concerns over valuation, regulatory pressure, or the pace of actual monetization.
In the last 24 hours, trading patterns in major AI-linked indices and mega-cap technology stocks underscore this push and pull. On the one hand, news of ongoing AI infrastructure investments and expanding partnerships with model developers has supported the sector’s relative strength compared with more cyclical areas of the market. On the other hand, any indication of cautious spending by enterprise customers or delays in commercial AI deployments can trigger profit-taking in the most richly valued names.
From a portfolio construction standpoint, this environment favors a barbell approach within AI: combining core exposure to established infrastructure and semiconductor leaders with selective positions in software and platform companies that have clearer paths to AI monetization. The key is distinguishing between firms that are primarily beneficiaries of AI capex cycles and those that must navigate a longer and more uncertain journey toward AI-driven revenue scale.
Frontier Models and Cloud Platforms: Scaling Multimodal AI
Parallel to the hardware buildout, the rapid advancement of frontier LLMs and multimodal AI capabilities is driving higher utilization of AI infrastructure. Leading model labs and cloud providers are rolling out increasingly sophisticated tools that integrate text, image, audio, and code, designed to function seamlessly within enterprise workflows and consumer products. Each new generation of models tends to be more parameter-intensive and computationally demanding, further reinforcing the need for dense GPU clusters and optimized data center architectures.
At the same time, there is a discernible shift from pure research toward enterprise-ready AI offerings, including security, compliance, and integration features. This enterprise orientation is critical for sustaining AI infrastructure demand beyond initial experimentation. As more enterprises commit to production deployments of AI agents, copilots, and domain-specific models, they require predictable performance, uptime, and governance—all of which depend on robust and scalable data center infrastructure.
For investors, the interaction between frontier model development and cloud-based AI services creates multiple layers of potential value creation. Semiconductor companies capture demand for compute and networking, cloud providers monetize AI services and platform fees, and software vendors build higher-margin applications on top. The current wave of infrastructure announcements signals that this stack is moving from concept to execution, with capital flowing across all layers.
Regulation, Energy and the Economics of AI Data Centers
Another critical dimension of the AI data center race is the growing attention from regulators and policymakers. Authorities in the United States and other major jurisdictions are examining the implications of large-scale AI deployments for energy consumption, grid stability, data privacy, and systemic risk. While specific legislative actions are still evolving, the direction of travel is toward more structured oversight and disclosure requirements for large AI infrastructure projects.
For the sector, this introduces both risks and opportunities. Stricter standards around energy efficiency and safety may raise compliance costs and lengthen project timelines. However, they also create barriers to entry and favor well-capitalized players with the ability to invest in advanced cooling technologies, renewable energy sourcing, and secure data handling practices. Large cloud providers and chipmakers that can align their infrastructure strategies with emerging regulatory frameworks may ultimately gain competitive advantage.
From a financial perspective, the energy footprint of AI data centers is becoming an essential input in long-term cost modeling. As AI workloads scale, electricity and cooling costs represent a non-trivial share of total operating expenses. Companies that successfully optimize for performance per watt and integrate renewable energy solutions will be better positioned to defend margins over time, even if headline compute demand continues to climb.
Implications for AI-Exposed Equities and Sector Positioning
Taking these strands together, the latest focus on AI data center buildout and GPU infrastructure has several implications for equity investors:
Sustained demand for AI chips: The multi-year nature of infrastructure commitments supports a structurally elevated demand profile for high-performance GPUs and accelerators, benefiting leading AI semiconductor names.
Supportive backdrop for cloud and hyperscale operators: Companies that can translate AI infrastructure into sticky platform revenue—through AI services, APIs, and consumption-based pricing—are likely to see recurring benefits beyond the initial capex cycle.
Selective upside in AI software and applications: As infrastructure becomes more widely available, the differentiation increasingly shifts to software layers that deliver domain-specific value, where margins are higher but competition is intense.
Higher volatility and valuation dispersion: Short-term trading may remain choppy as markets balance enthusiasm for AI’s long-term potential against questions around near-term profitability and capital intensity.
For institutional portfolios, this environment argues for a structured framework to categorize AI exposure. Hardware and infrastructure leaders can be viewed as core holdings tied to the buildout of compute capacity. Cloud and platform companies represent leveraged plays on AI utilization and enterprise adoption. Application-layer firms offer optionality on breakthrough business models but require careful scrutiny of product-market fit and pricing power.
Outlook: The Next Phase of the AI Infrastructure Cycle
Looking ahead, the trajectory of the AI sector will be shaped by how efficiently companies can convert infrastructure investment into monetizable AI products and services. The near-term news flow around new data center projects, GPU procurement, and cloud AI partnerships suggests that the industry is entering a second phase of the cycle: moving from proof-of-concept deployments to scaled, revenue-generating applications.
While the pace of adoption will vary by industry, the strategic commitment of major technology and cloud providers to AI infrastructure reduces the likelihood of a sharp demand reversal. Instead, investors should expect periodic consolidations and sentiment-driven corrections within an overall upward trend in AI-related earnings power. The sector’s leadership will likely remain centered on companies that can command both the economics of compute and the economics of software.
In that context, the current focus on AI data centers and GPU buildout is more than a short-lived headline. It reflects a structural reallocation of capital toward the computational backbone of modern AI, with far-reaching consequences for semiconductor makers, cloud platforms, and AI-driven software vendors. For now, the balance of evidence supports a cautiously bullish stance on the broader AI ecosystem, anchored by the tangible, rapidly scaling investment in the infrastructure that will power the next generation of intelligent applications.